Australians are better informed about their health and wellness than ever. The deluge of data from wearables and apps and the constant stream of health-related information from AI and social media have pushed health, fitness, and mental wellness into the mainstream. A space once preserved for healthcare professionals and formal care settings is opening up to consumer companies as the focus shifts from cure to prevention.
Everyday health has become a rhythm, not a resolution
This rise of “everyday health” in Australia is showing up in consumer aspirations, behaviours, and spending habits. To understand how health aspirations and behaviours are changing, PwC’s Voice of the Consumer 2026 survey gathered 21,808 responses from consumers in 27 countries, including 1,001 in Australia.
Our research points to three things that define how Australians manage their health today.

Embracing health tech, but sceptical of sharing their personal health data.

More physically active than consumers globally, yet rating their overall health lower.

Consulting AI on health issues, but still trust their healthcare providers more.
A future of care is emerging that is increasingly connected, self-managed, and personalised. Opportunities abound for consumer goods companies, retailers, and healthcare professionals that can think beyond traditional products and services to deliver joined-up solutions that meet Australians’ higher aspirations for healthy living.
“Consumers are more advanced and have better literacy around what’s going on with their health. They’re using technology, they’re researching things, and they are much more active participants in their care.”
Nicola Lynch,Health & Education Industry Leader, PwC AustraliaIn this report
How Australians rate their health today. What they hope for their health and wellbeing. The growing influence of tech, AI and weight-loss drugs.
Read the findings
The health and wellness consumer orbit
How goals and mindsets translate into consumer behaviour, across daily routines, the weekly rhythm and monthly and annual events.
View the orbit
Implications and opportunities for consumer companies
Meeting the changing needs of Australian consumers, for food, beverage and supplements, home and personal care, omnichannel retail and healthcare providers.
Explore by sector
What the survey found Three themes shape how Australians manage their health
Australians are more active than global peers, yet feel less healthy

More than 1 in 3 Australians (35%) rate their current health as poor or life-restricting, with women (43%) far more likely than men (27%) to have a negative perception of their health.

Sleep tops the list of health concerns, with 1 in 2 Australians worrying about sleep quality.
Australia is known for its outdoor living and active lifestyles, but this simplistic portrayal of Australian health and wellness masks a more nuanced reality. Australians cast harsher judgment on their health than other survey respondents globally. More than a third (35%) say their current health is poor or life-restricting; 7 percentage points higher than the global average of 28%.
How would you rate your current level of health?
For women, the picture is worse: 43% of Australian women see their health as poor or life-restricting, versus 27% of Australian men. And there’s a difference between the generations, too, with Gen-Xers rating their health lower than both Millennials and Boomers.
Specific health concerns also differ across the age groups. Gen Z are more concerned with the quality of their sleep and their mental health and emotional well-being than Boomers, who in turn are more concerned about their cardiovascular health and their physical fitness and strength.
Despite these health concerns — or perhaps, because of them — 3 in 4 Australians invest in outdoor activities and proactive nutrition to achieve their health and wellness goals. Supplements are the dominant wellness purchase, with 6 in 10 Australians buying them in the last year.
While not all Australians consider themselves the picture of good health, the nation largely lives up to its reputation for health and fitness. Australians spend more time outdoors and on physical fitness routines than the global average. Mental health is a big focus too, with sleep tracking, brain training, meditation, and counselling all seeing greater uptake in Australia than among survey respondents globally.
“There’s a real paradox in the data. We’re a nation known for outdoor living and physical activity, yet more than a third of Australians rate their health as poor or life-restricting, well above the global average. More data hasn’t made us feel healthier, it’s raised the bar on what ‘healthy’ even means.”
Andrew Aoukar,Retail & Consumer, PwC AustraliaHealth has shifted from a clinical goal to a daily lifestyle pursuit

“Stress, fatigue or low energy” is the top barrier to improved health, with nearly 2 in 3 Australians (64%) citing this as the main hurdle to meeting their health and wellness goals.

Australians are more “overwhelmed by information” than consumers globally, rather than having a “lack of information” (-5 points compared with the global average).
Good health is no longer about simply preventing clinical conditions. Australians are embracing a more holistic sense of their well-being, encompassing traditional health goals like living longer or losing weight, alongside wellness-oriented ambitions for better mental health, sleep, and personal growth.
But ambition does not always translate into action — for a number of reasons. Nearly two-thirds (64%) of Australians struggle with “stress, fatigue, or low energy” in trying to meet their health and wellness goals. Next on the list of barriers are “difficulty staying motivated or consistent” (55%), “balancing health and wellness goals with other priorities” (54%), and “lack of time to commit” (52%).
Stressed and busy Australians may have less time or energy to focus on their health than they’d like, but they are certainly not lacking information to support their wellness journeys. Australians rely on authoritative and expert voices as the strongest influence on their health and well-being actions, with 61% saying recommendations from healthcare professionals matter most, versus 57% globally. Australians’ own curiosity about their health and wellness is the next strongest influencer.
The expanded scope of what good health looks like — combined with the reams of health advice available to consumers today — is driving growth in the wellness category.
“Longevity is the number-one health goal for 21% of Australians, but it sits alongside sleep, stress reduction and mental wellbeing. People aren’t only asking, ‘How do I live longer?’ They’re also asking, ‘How do I feel better while I do it?’”
Mayank Nayak,Strategy&, PwC AustraliaConsumers are increasingly managing their health through technology, data, AI and diagnostics
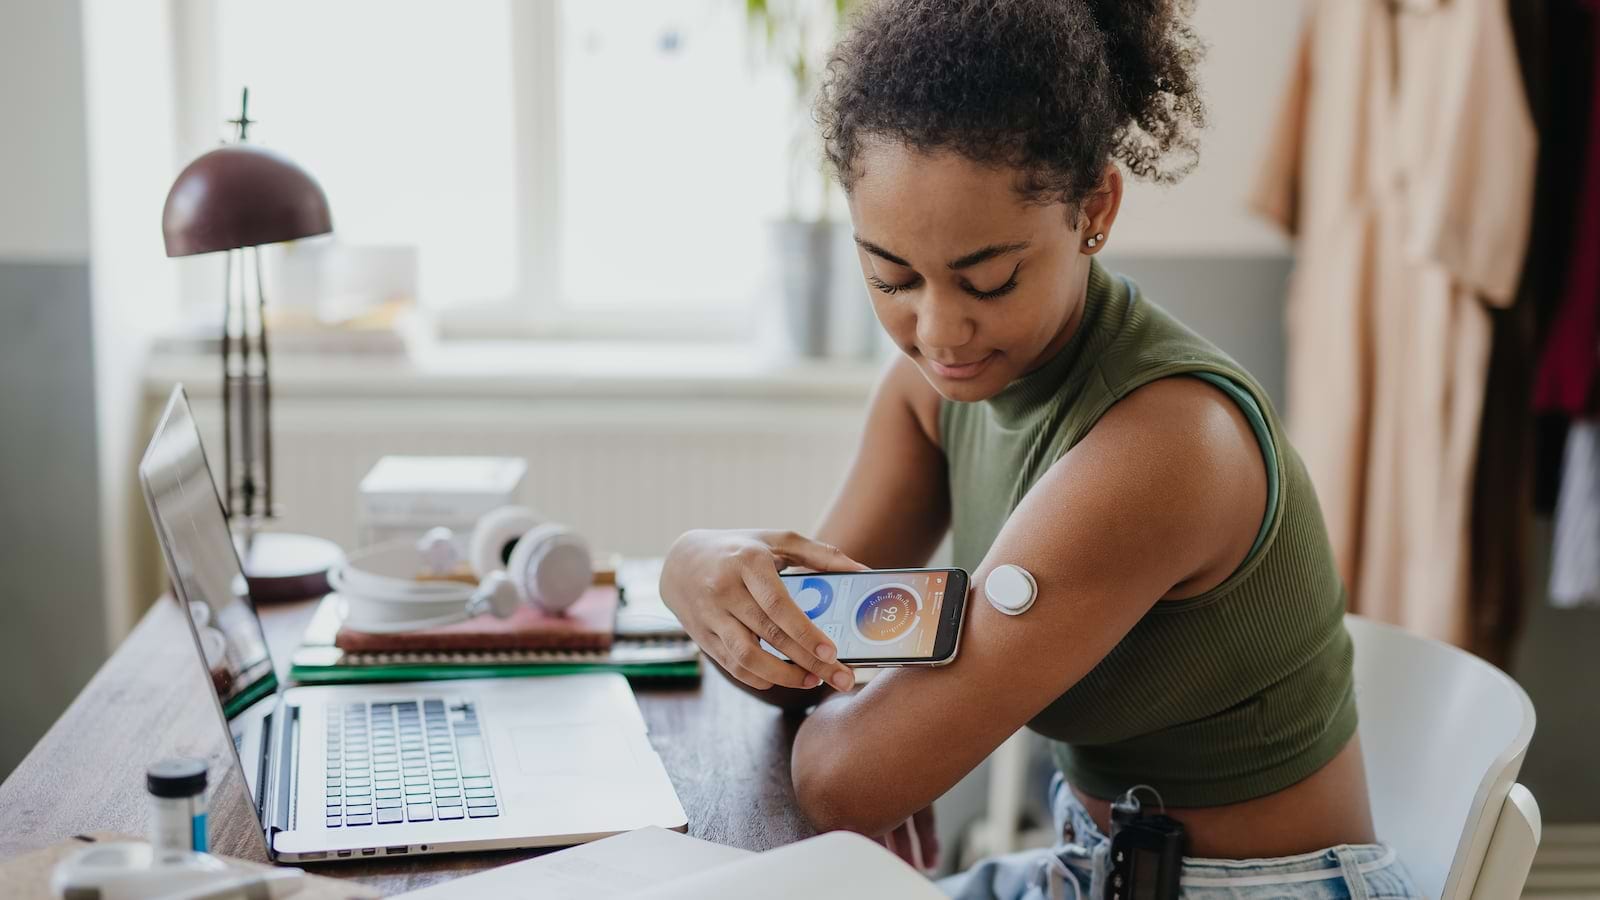
Health-focused technology is huge: 4 in 5 Australians (82%) now use healthcare apps and wearables, up from 68% a year ago and higher than the global average of 80%.

At least half a million Australians are taking GLP-1 weight-loss drugs every month.1
Australians’ negative health perceptions and information overwhelm may be partly linked to the nation’s enthusiastic adoption of technology. Some 82% of Australians now use healthcare apps and wearables, with the top use cases being exercise instruction and monitoring (40%), medication reminders (38%), and sleep tracking (34%).
AI is quickly gaining ground in the health and wellness space, too, as Australians take greater control over their own health. Nearly two-thirds (63%) of Australians now reportedly use AI before consulting a healthcare professional.
But even as Australians embrace technology and AI, they are not ready to hand over their personal health information to just anyone. Only a fifth of consumers (20%) say they are open to broad sharing of their health information across service providers. More than half of consumers (52%) are not willing to share health data with media apps or services, banks (51%), food and drinks companies (49%), or technology companies (48%) — even if that information is used to offer them more personalised products and services. Pharmacies are the most trusted product or service provider for handling sensitive health information.
GLP-1 use is growing exponentially globally, and at least half a million Australians are now taking them every month, with many more expected to jump onto the trend. Those using GLP-1s appear to be doing so for more than weight loss alone and are more engaged in managing their health than non-users, on average. They are also more likely than non-users to monitor their intake of fibre, protein, and calories, and to practice intermittent fasting or time-restricted eating.
A majority of GLP-1 users report clear behaviour change in a range of health-related areas since taking weight-loss prescription medication. Nearly two-thirds (64%) say taking the drugs has impacted their attention to nutrition, the amount they exercise (63%), and their spending on food (58%).
Australians who have the financial means appear to be willing to spend big to access GLP-1s. Almost half of Australia’s GLP-1 users are buying them privately for up to $600 per month.2 Users also say they plan to increase their overall spending on health and wellness, personal style and appearance, and food.
“Health advice used to travel down the generations. It now travels up. The fastest adoption channel in this market isn’t marketing, it’s a 25-year-old setting up their grandmother’s glucose monitor.”
Samantha Jansen,Retail & Consumer, PwC AustraliaFrom goals to behaviour The health and wellness consumer orbit
How goals and mindsets translate into consumer behaviour
Health and wellness habits are now part of everyday life for many Australian consumers, impacting their daily, weekly, and longer-term routines and spending behaviours.
Daily routines: From wake-up to lights-out, health-related habits map across every part of the day. Australians start their mornings by checking their sleep scores and preparing their mind and body for the day ahead with gentle movement and breathing. They focus on nutrition and protein-rich meals to drive midday performance and schedule exercise and self-care routines for the late afternoon. Evenings are for recovery, with a growing focus on winding down the body and mind to prepare for restful sleep.
Weekly rhythm: As Australians embrace a holistic approach to health, many are dedicating time each week to their physical, mental, and social well-being. The physical track is all about movement and socialising and might include a weekly group sport session or gym class, outdoor activities at the weekend, and a focus on physical recovery. The mental track is about resetting and restoring the mind, featuring therapy, yoga, meditation, and wellness workshops. And the social track is where Australians measure and share their progress, assessing data from their wearables and apps, earning rewards for their efforts, and restocking supplements for the week ahead.
Monthly and annual events: Health goals or interventions also map across longer time horizons, from full-body health checks once a year to restorative retreats and getaways. The focus here is on renewal, encompassing formal diagnostics and health screenings, transformational goals around weight-loss and appearance, and restoration. This is also where Australians pay attention to health-focused services, seeking value on subscriptions and premiums and maximising rewards for healthy behaviour.
“Our research shows that health has become a rhythm, not a resolution, mapping across the entire day, sleep scores at wake-up, protein at midday, recovery at night, and across the week and year. This shift opens up countless touchpoints for brands to influence consumer health habits.”
Andrew Aoukar,Retail & Consumer, PwC AustraliaImplications and opportunities for consumer companies Meeting the changing needs of Australian consumers
As health and wellness needs evolve and expand, companies across the health and wellness spectrum can become more targeted in their support for Australians on their individual health journeys.
Food, beverage, and supplements companies
Food is becoming functional and supplements are commonplace. Australians are managing energy, satiety, sleep, and weight through their diet, with a particular focus on fibre and protein intake. Vitamins, minerals, and supplements were the number-one health purchase among Australians over the past 12 months.
The market is by no means saturated, with consumers planning to increase their intake of fresh produce and supplements. Many also signal an intention to cut down on ultra-processed and high-sugar foods, as well as alcohol. GLP-1 adoption, meanwhile, has increased demand for high-protein, smaller-portion, satiety-focused formats.
Companies can move away from general “better-for-you” claims towards functional outcomes from food consumed throughout the day:
New products catering to evolving everyday needs: Develop protein-rich breakfasts to support energy, healthy afternoon snacks to replace confectionery, and sleep teas and meal options designed to protect sleep scores, for example.
Personalised supplement subscriptions: Help consumers understand what to consume, when, and how it supports their goals, and leverage high app and wearables use to explore new connected packaged services, such as daily or weekly supplement packs that replenish automatically, but keeping data controls and privacy in mind.
GLP-1 companion nutrition: Explore high-protein, muscle-preserving foods, with tiered ranges to cover both accessible and premium price points. Cater for GLP-1 users by offering smaller-portion formats.

Home and personal care
The three-track view of health and wellness — physical, mental, and social — draws the home environment and personal care routines deeper into the health space.
Around half of Australians have concerns about their sleep quality, and the popularity of wearables and health tech means more Australians are paying attention to it. Future health spend may continue moving into the hardware and the home environment, with over half of Australian consumers planning to spend on health technology and equipment, as well as ambient or sensory wellness products.
Companies can move away from a product focus to an environment focus, with solutions that support sleep, recovery, beauty, and daily well-being:
The home as a health environment: Position the bathroom cabinet and bedroom as well-being zones across morning routines and evening wind-downs. Develop fitness equipment for at-home convenience, such as PEMF (pulsed electromagnetic field) mats designed to reduce inflammation and support recovery at home.
Diagnostic-led personalised routines: Turn weekly self-care moments into tailored, interconnected regimens that combine technology, health data, and the home environment to personalise prompts around when to train, rest, or wind down. Leverage technology like at-home skin analysis tools to support personal care routines.
Restorative reset and recovery bundles: Develop sensory, recovery, and sleep environment kits to support the strong appetite for restorative solutions among Australian consumers, focusing on the premium and super-premium market segments.

Omnichannel retail
As the typical Australian consumer becomes more comfortable using technology to proactively manage their health, omnichannel retail will emerge as the place where consumers navigate their endless health choices.
Retailers will need to reorganise how they cater for consumers, focusing on goals related to sleep, stress, weight management, and energy rather than on traditional product aisles and categories. Bundled solutions and services — especially when tailored for individual consumers — are a powerful way to convert frequent consumer activity into cross-category spend.
Retailers can become the trusted place where consumers navigate health choices:
Goal-based navigation, not categories: Organise product ranges around health outcomes such as sleep, stress, weight management, and energy by bundling food, supplements, devices, diagnostics, and advice — catering for both value-conscious and aspirational shoppers.
Extending the product–service continuum: Tap into the growing trend of “nootropics” that focus on memory, productivity, and brain health. Consider new in-store services such as skin diagnostics and personalised skincare recommendations, and leverage loyalty programmes and customer preference data to support personalised health journeys.

Healthcare providers
Just as health-focused products and services permeate the consumer space, traditional healthcare providers have new opportunities to meet changing consumer needs. The consumerisation of health is expected to show up most strongly at the prevention stage of healthcare management.
Australians today have high trust in traditional healthcare providers, but they are also open to exploring different ways of receiving care: 72% say they received care in a doctor’s office, but only 34% say they prefer it in the future. Pharmacies could play an increasing role, given that consumers are more willing to share their personal health information with pharmacies over any other type of company or service provider.
Healthcare providers can move from treatment to prevention, engaging earlier to support everyday health routines:
The pharmacy as the trusted health hub: Leverage the consumer trust premium in pharmacies to help Australians achieve their health and wellness goals. Shift from dispensing medication to offering solutions like digital delivery or counselling, and introduce smart in-store kiosks for diagnostic insights that guide supplement recommendations.
Earlier, lower-friction engagement: Use sleep, stress, weight, and digital triage data as everyday entry points to better health, matching the retail-like convenience Australians now expect in a healthcare setting. Combine health data, at-home monitoring tools, AI summaries, and doctor oversight into prevention plans that support early risk detection and intervention.
Prevention and the “carer-shopper”: Design solutions for family members providing at-home support for relatives through recurring, relationship-based engagement that builds on the healthcare provider trust premium. Develop services that span the physical, mental, and social health tracks and orchestrate the journey from awareness to outcomes through ecosystem partnerships anchored in rigorous privacy and data-sharing standards.

“As spending moves upstream, consumer companies have a greater role to play in prevention. The opportunity is to help people act earlier with better information, everyday products that support healthy living, and services that make healthier habits easier to sustain.”
Birger Maekelburger,Strategy&, PwC AustraliaVoice of the Consumer 2026: Australian insights
Read the full Australian findings on how everyday health is reshaping consumer behaviour, spending and expectations.
About the authors