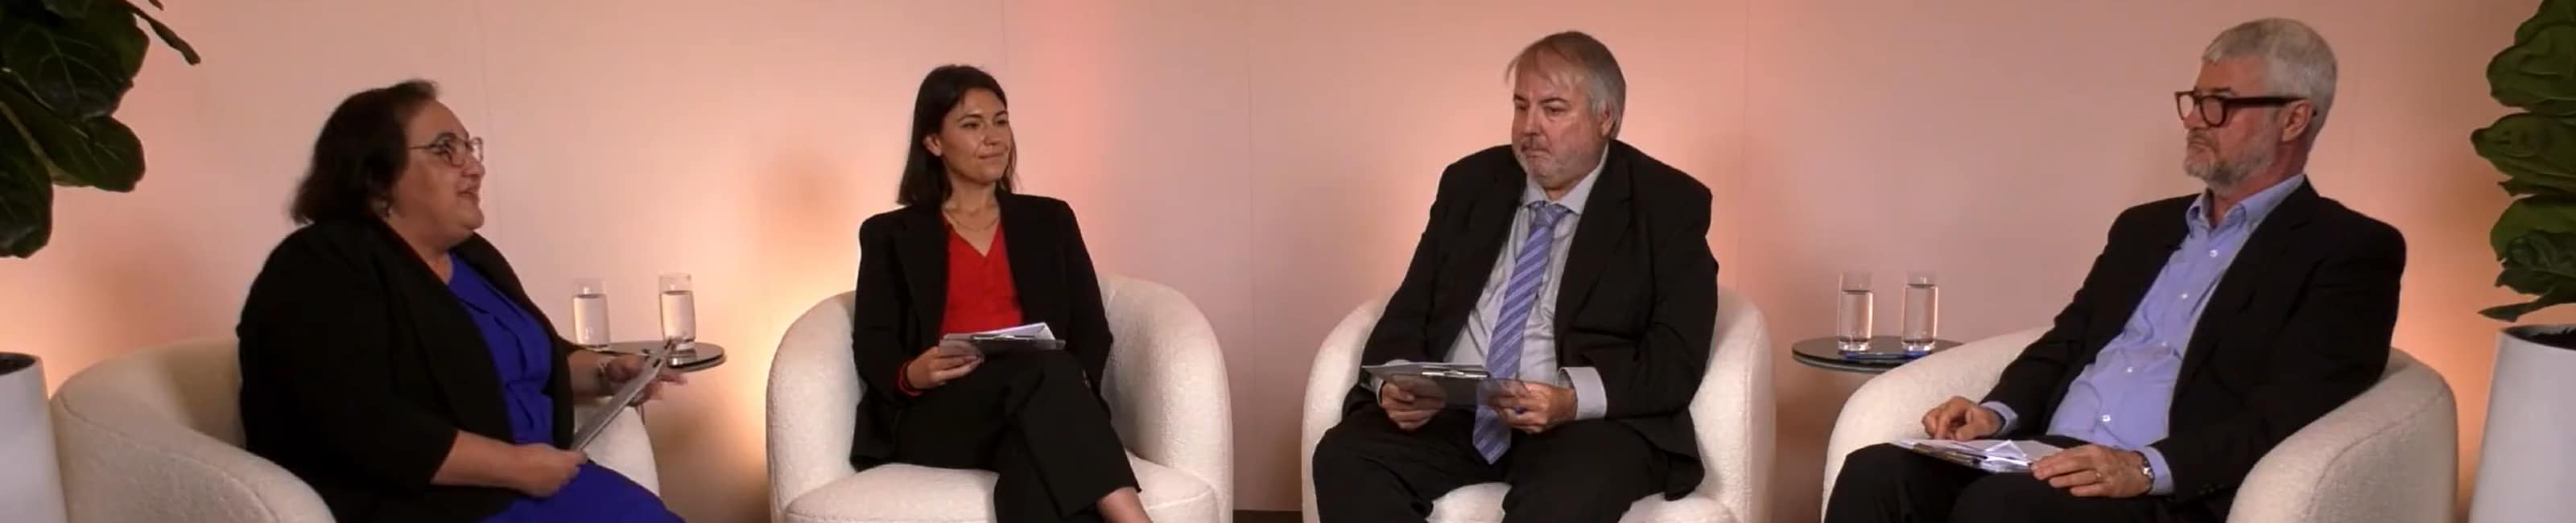
ATO Assistant Commissioners Jonathan Todd and Michael Ingersoll joined PwC’s September Tax Briefing to share lessons from the first reporting cycle of Australia’s public country-by-country reporting and Pillar Two Global and Domestic Minimum Tax regime.
Hosted by Patricia Muscat, the webcast also featured PwC Partner Tariq Rasool from the corporate and international tax team, specialising in International Tax, and PwC Director Diana Costan from the transfer pricing team, who works on country-by-country reporting. The discussion emphasised early preparation, integrated data, and robust documentation as reporting obligations evolve.
First public country-by-country cycle reveals practical challenges
The first reporting cycle attracted hundreds of lodgments. Key challenges included assessing whether entities were in scope, navigating registration and exemption processes, reconciling data across reporting requirements, and confirming representative authority. Clear ownership across tax, finance, and legal teams is critical.
The ATO checks that a report has come from the relevant entity and meets the law and approved-form requirements. Reports are expected to be published in November 2026 on data.gov.au, and the ATO encouraged entities to consider how they will contextualise their information.
Exemptions are assessed case by case and are granted only in exceptional circumstances. The Commissioner will have regard to a range of matters set out in PS LA 2025/2. Given the evidentiary burden involved (which is likely to require coordination across multiple stakeholders within the group) entities considering an exemption application should begin preparations well in advance and engage with the ATO at the earliest opportunity.
Pillar Two shifts the focus to future readiness
Initial challenges were largely administrative, as transitional country-by-country reporting safe harbours reduced the technical burden for many groups. Groups must still document their eligibility, supporting figures, and source records. The ATO indicated that it had not yet received formal requests for penalty relief and encouraged taxpayers seeking to demonstrate reasonable compliance efforts to focus on record keeping and documenting their circumstances and measures taken.
Businesses should use the transitional period to review deferred tax balances, model outcomes outside safe harbours, and assess Pillar Two implications during acquisitions. Incomplete schedules, unreconciled balances, or approximate entries may generate top-up tax that might not otherwise arise. Tariq also noted that when an Australian group acquires an entity and brings it into a consolidated group, the tax cost base reset may not be matched by a corresponding step-up in carrying values for GloBE purposes, potentially affecting the Pillar Two effective tax rate calculation.
The ATO’s risk-based approach will focus on non-lodgments, cases where profiling indicates that top-up tax should or could arise but none is reported, and cases where a taxpayer may not be eligible for a claimed safe harbour. Groups should also prepare for announced changes to the GloBE Information Return and future reviews of whether jurisdictions have qualifying Pillar Two regimes.
Integrated data and governance support reporting readiness
Public and confidential country-by-country reporting and Pillar Two obligations should be managed together. Early gap analysis, consistent data, reliable audit trails, and technology-enabled data extraction can reduce duplication and help groups prepare country-by-country reporting information for use in their Pillar Two calculations.
Overall, groups should start early, involve relevant stakeholders, integrate their data, and maintain contemporaneous documentation as transparency and Pillar Two reporting requirements evolve.
Access this Tax Briefing on demand via the video link below.


